Consumer Bankruptcy Leads: Attorney Screening and Follow-Up
Structure consumer bankruptcy leads attorney screening and follow-up to convert more inquiries into filings. Call (510)-663-7016 for lead strategy help.
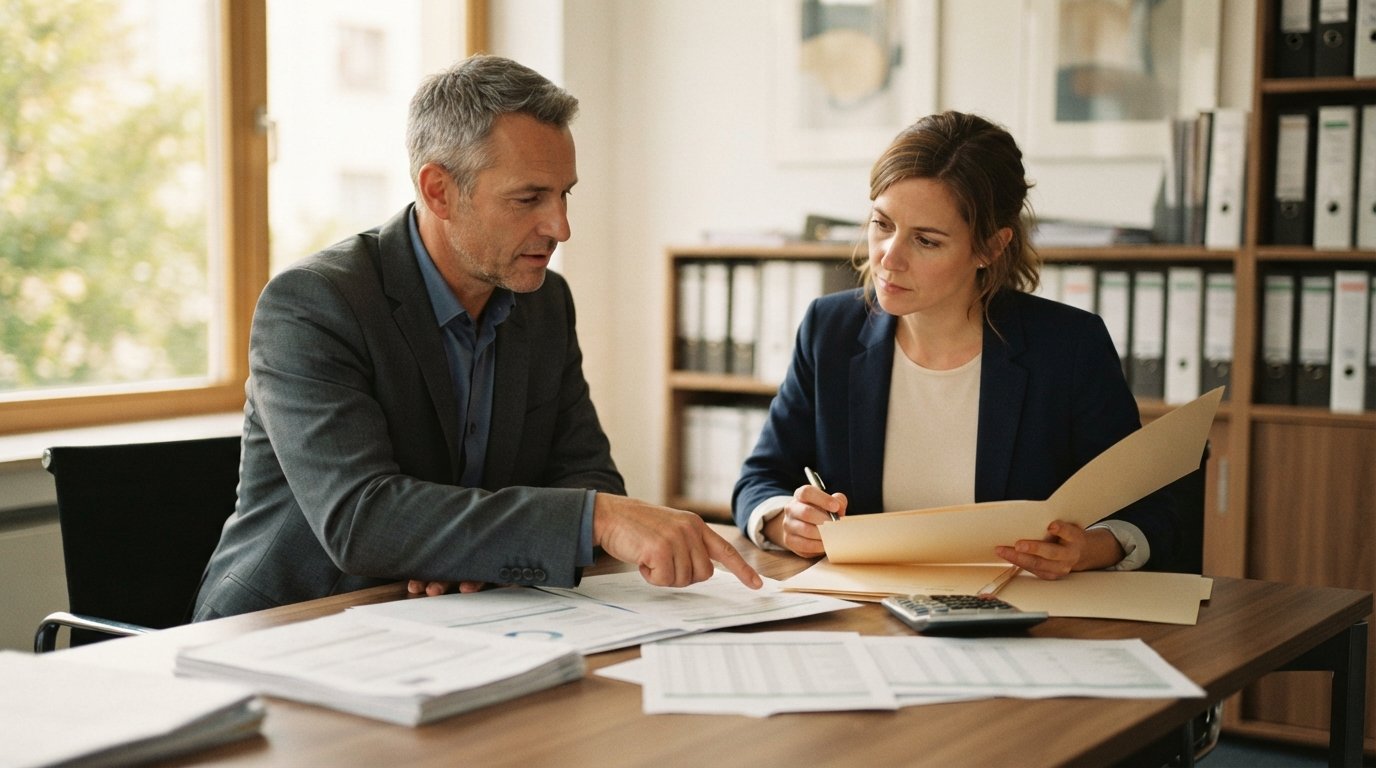
Consumer bankruptcy leads arrive with urgency, but urgency alone does not pay the bills. The difference between a full consultation calendar and a stack of unqualified inquiries comes down to two disciplines: structured screening and persistent, compliant follow-up. Attorneys who master both convert more consumer debt prospects into retained clients, while those who skip these steps waste billable hours on callers who were never eligible or never serious. This article breaks down how to screen Chapter 7 and Chapter 13 prospects, which financial details matter most, how to follow up without crossing compliance lines, and how to track every inquiry from first contact to filed petition.
Why Screening and Follow-Up Decide ROI on Consumer Bankruptcy Leads
Bankruptcy leads are not commodity clicks. A consumer who searches for debt relief is often under financial stress, comparing several attorneys, and unsure whether they even qualify for filing. That combination makes early screening essential. Without a disciplined intake process, your team spends precious consultation slots on prospects whose income exceeds Chapter 7 thresholds, whose prior discharge bars a new filing, or who are simply price shopping with no intention to retain.
Follow-up matters just as much. Consumer debt prospects rarely retain on the first call. They need time to gather pay stubs, tax returns, and creditor statements, and they often want to compare options before committing. A structured follow-up cadence keeps your firm visible during that decision window without becoming a nuisance. When screening and follow-up work together, the math changes: fewer wasted consultations, higher show rates, and a cleaner pipeline from inquiry to retained filing. Firms that treat lead acquisition as a system rather than a one-time purchase consistently outperform those that buy leads and hope for the best. If you are weighing whether purchased leads fit your practice model, our breakdown of the pros and cons of buying legal leads is a useful starting point before you build the screening layer on top.
Chapter 7 Versus Chapter 13: Screening Questions to Ask Up Front
The first five minutes of any consumer bankruptcy conversation should determine which chapter, if any, fits the prospect. Asking the right questions early protects your consultation time and signals professionalism to the caller. Start with the means test inputs: household size, gross income from all sources over the past six months, and whether income has changed recently. A prospect who fails the Chapter 7 means test is not a dead lead; they may be an excellent Chapter 13 candidate, so route them accordingly rather than ending the call.
Next, move to the nature of the debt itself. Ask whether the debts are primarily unsecured (credit cards, medical bills, personal loans) or secured (mortgage arrears, vehicle loans). Ask whether any creditor has filed a lawsuit, garnished wages, or threatened repossession, because active collection pressure changes the urgency and sometimes the chapter choice. Finally, confirm residency and venue, since bankruptcy is filed where the debtor has lived for the majority of the prior 180 days.
A practical screening script covers five areas in sequence:
- Household composition and gross monthly income for the last six months
- Debt types, balances, and whether any are secured or subject to active collection
- Assets such as home equity, vehicles, bank balances, and retirement accounts
- Prior bankruptcy filings and discharges within the relevant lookback periods
- Urgency indicators: garnishment, foreclosure dates, repossession threats, or lawsuit deadlines
Train intake staff to capture these answers in a structured form rather than free text. Structured data lets you score leads, prioritize callbacks, and spot patterns in which sources produce filable cases. It also makes the attorney consultation faster, because the prospect arrives with facts already on file instead of repeating their story three times.
Income, Asset, and Prior Filing Details That Affect Eligibility
Income analysis goes beyond a single paycheck. The means test uses a six-month lookback, so a prospect who recently lost a job or received a bonus may have income that looks very different from their current reality. Capture gross income by month, note any lump sums, and flag self-employment income separately, since Schedule C deductions and irregular deposits require closer review. Household size matters too: a prospect supporting an elderly parent or adult child may qualify with a larger household count, so ask who lives in the home and who shares expenses.
Assets deserve equal attention. Home equity above the applicable exemption, non-exempt vehicles, recent large transfers to family members, and cryptocurrency holdings can complicate a Chapter 7 filing or push a prospect toward Chapter 13. Ask directly about transfers or sales of property in the past two years, because trustees scrutinize those transactions and a prospect who fails to disclose them creates risk for both parties. Prior filings are the third pillar: confirm whether the prospect received a Chapter 7 discharge within the last eight years or a Chapter 13 discharge within the last six, and whether any prior case was dismissed for failure to comply. These details determine whether a filing is even possible, let alone advisable.
Document collection should begin during screening, not after retention. Request recent pay stubs, the last two tax returns, creditor statements, and a photo ID. Prospects who hesitate to provide documents are often not ready to file, and knowing that early saves your attorneys hours of follow-up. A simple document checklist sent immediately after the first call increases completion rates and gives your team a concrete reason to follow up.
Building a Follow-Up Cadence for Prospects Still Deciding
Most consumer bankruptcy prospects do not retain on day one. They are weighing Chapter 7 against debt consolidation, waiting for a paycheck, or discussing the decision with a spouse. A follow-up cadence keeps your firm in the conversation without pressure. The goal is to be the attorney they remember when they finally decide to act, not the one who called eleven times in a week.
A workable cadence for consumer debt leads looks like this:
- Same-day response: call within minutes of the inquiry, then send a text or email confirming the conversation and the next step.
- Day two: a brief check-in offering to answer questions about the documents or the process.
- Day seven: a value touch, such as a short explanation of what happens at the 341 meeting or how garnishment stops after filing.
- Day fourteen: a direct but respectful check on whether they are ready to schedule a consultation.
- Day thirty and monthly thereafter: a low-frequency nurture message until the prospect opts out or files elsewhere.
Personalize each touch with the facts captured during screening. Referencing the prospect's garnishment date or their question about their car loan shows the follow-up is not automated noise. Track responses and disposition codes carefully, because a prospect who says "not now" in month one may file in month four, and firms that stop following up after two attempts leave recoverable revenue on the table. The same discipline applies whether you generate leads in-house or buy them; the intake system, not the lead source, determines how many of those prospects become clients.
Compliance Considerations for Consumer Debt Communications
Consumer bankruptcy prospects are consumers first, and communications with them fall under a patchwork of rules. The Telephone Consumer Protection Act restricts autodialed calls and texts to cell phones without prior express consent, and the Fair Debt Collection Practices Act governs debt collectors rather than attorneys advising debtors, but state-level rules and bar advertising regulations add further layers. The safest posture is consent-first: capture written consent for calls and texts at the point of inquiry, honor opt-outs immediately, and document everything.
Advertising rules matter as well. Bankruptcy attorneys must avoid misleading claims about outcomes, and some jurisdictions restrict how firms present debt relief services. Keep marketing messages factual, avoid promising discharge, and ensure any lead vendor you work with verifies consent and sources inquiries transparently. Reputable platforms build verification into their process, and firms should ask pointed questions about how leads are generated, how consent is captured, and how shared versus exclusive distribution works. Compliance is not a constraint on growth; it is the foundation that keeps your pipeline defensible if a consumer complaint or bar inquiry ever arrives.
Data handling deserves the same care. Store prospect information securely, limit access to intake staff who need it, and purge records according to your retention policy. When you work with a lead provider, confirm that their data practices meet your obligations, because your firm's reputation travels with every inquiry you accept.
Tracking Conversion from Inquiry to Retained Filing
You cannot improve what you do not measure. Build a simple funnel report that follows each consumer bankruptcy lead through five stages: inquiry received, screening completed, consultation scheduled, consultation held, and case retained (with a final column for petition filed). Assign disposition codes at every stage, including reasons for rejection such as means test failure, prior discharge, or no response. Within a quarter, patterns emerge: which lead sources produce filable cases, which intake staff convert best, and where prospects fall out of the funnel.
Two metrics deserve weekly attention: contact rate (the percentage of inquiries your team reaches within the first hour) and consultation show rate. Both are leading indicators of revenue, and both respond quickly to process changes. If contact rate is low, revisit staffing and response time. If show rate is low, strengthen reminder sequences and confirm documents before the appointment. Firms that want a steady stream of high-intent consumers can pair these internal metrics with a verified lead source; platforms such as MortgageLeads demonstrate how real-time, filtered lead delivery works in a related financial vertical, and the same principles of verification and intent apply to consumer debt inquiries.
Finally, close the loop with your lead provider. Share anonymized conversion data so distribution can be tuned toward the profiles that actually file. Screening and follow-up are not back-office chores; they are the engine that turns consumer bankruptcy leads into retained clients and predictable firm growth.
Consumer bankruptcy leads reward firms that treat intake as a discipline. Screen for chapter eligibility and financial detail before the consultation, follow up on a cadence that respects the prospect's decision timeline, keep every communication compliant, and measure conversion at each stage. Do those four things consistently, and your lead spend becomes an investment with a measurable return rather than a gamble on unqualified inquiries.